- The market is shifting towards stricter regulation and smarter, AI-enabled devices
- Expansion into lower-tier cities and international markets accelerates
- Regulatory costs and advanced technology are reshaping industry competition
China’s RF Medical Aesthetics Market Moves into a More Regulated, Tech-Driven Phase
Frost & Sullivan recently published a new blue book on China's radiofrequency-based medical aesthetic devices industry, highlighting how the market is being reshaped by tighter regulations, faster adoption of new technology, and the growing ambitions of local companies to go international.
This report was published in September 2026, and it looks closely at China’s RF medical aesthetics industry chain, the current policy environment, what’s driving market growth, and how radiofrequency technology is evolving in non-surgical aesthetic treatments. According to Frost & Sullivan, the sector is heading toward smarter devices, increasing penetration into lower-tier cities, and a more globalized operating model for Chinese manufacturers.
The insights have implications not just for device makers, but also for electronics, sourcing, and logistics sectors too. From a sourcing perspective, regulatory registration and product intelligence are becoming essential for getting into the market. Distributors and procurement teams may need to consider a supplier’s ability to handle compliance issues, develop connected or AI-enabled systems, and support market-specific operations abroad.
RF Technology Still at the Heart of Non-Surgical Aesthetics
Frost & Sullivan explains that RF-based aesthetic systems work by delivering electromagnetic energy into tissues to produce heat. This heat prompts collagen contraction and regeneration, placing RF devices within the broader category of non-surgical, energy-based aesthetic treatments.
It’s part of a bigger shift where consumers and clinicians are leaning toward treatments that produce good-looking results without traditional surgery. People want shorter recovery times, safer workflows, and treatments tailored to their needs. And that push is nudging product development, manufacturers are trying to make their systems more precise, easier to manage, and adaptable for different treatment setups.
This broader trend toward AI-enabled personalization and technology that improves precision is becoming more prominent in the cosmetic and aesthetic space. Frost & Sullivan also pointed out that there’s a rising demand for smarter devices that can monitor, support safety, and offer more customized treatment workflows.
For electronics manufacturers and sourcing teams, that means the relationship between hardware and software becomes even more critical. RF devices aren’t just about energy transfer anymore; their market positioning increasingly depends on features like monitoring, user controls, safety functions, and the ability to support personalized treatments.
From a supply-chain perspective, suppliers involved in control systems, sensors, software, and device integration may become more important as RF platforms become more sophisticated. However, the report does not identify any one component or supplier as dominant. Instead, this article’s analysis suggests that product intelligence, meaning the software, controls, sensors, and related features, is becoming a more visible part of market competition.
Regulation as a Key Commercial Gatekeeper
Regulations are playing an ever-growing role in shaping China’s RF medical aesthetics market. Frost & Sullivan points out that the National Medical Products Administration (NMPA) has shifted away from somewhat relaxed oversight toward a much more stringent approval process.
They mention guidance issued in 2023 and a new rule that requires RF treatment devices to register as Class III medical devices starting in April 2026. The report notes that the registration process can cost over 10 million yuan. That kind of expense could squeeze smaller players and potentially accelerate industry consolidation.
This change isn’t just about legal status, regulatory requirements impact the entire product lifecycle, including R&D planning, documentation, testing, manufacturing, quality control, and time-to-market. Companies wanting to enter the market will need to consider these requirements much earlier, right from their sourcing and product development stages.
For buyers, regulatory readiness might become a crucial factor when evaluating suppliers. A device that looks attractive because it’s low cost or because the manufacturer’s production proposal seems solid might not be feasible if the supplier can’t handle the registration process. Essentially, expertise in navigating regulations could end up being a key differentiator among Chinese suppliers.
From this article’s analysis, increased compliance costs could also affect the industry’s economic landscape. Smaller firms that can’t absorb the registration expenses might struggle to compete independently, while larger, well-funded manufacturers may be better positioned to keep investing in product development and open new markets.
Smarter Products to Drive Future Growth
Frost & Sullivan points out that the next phase of growth will be heavily influenced by smarter product design, AI integration is becoming a major trend.
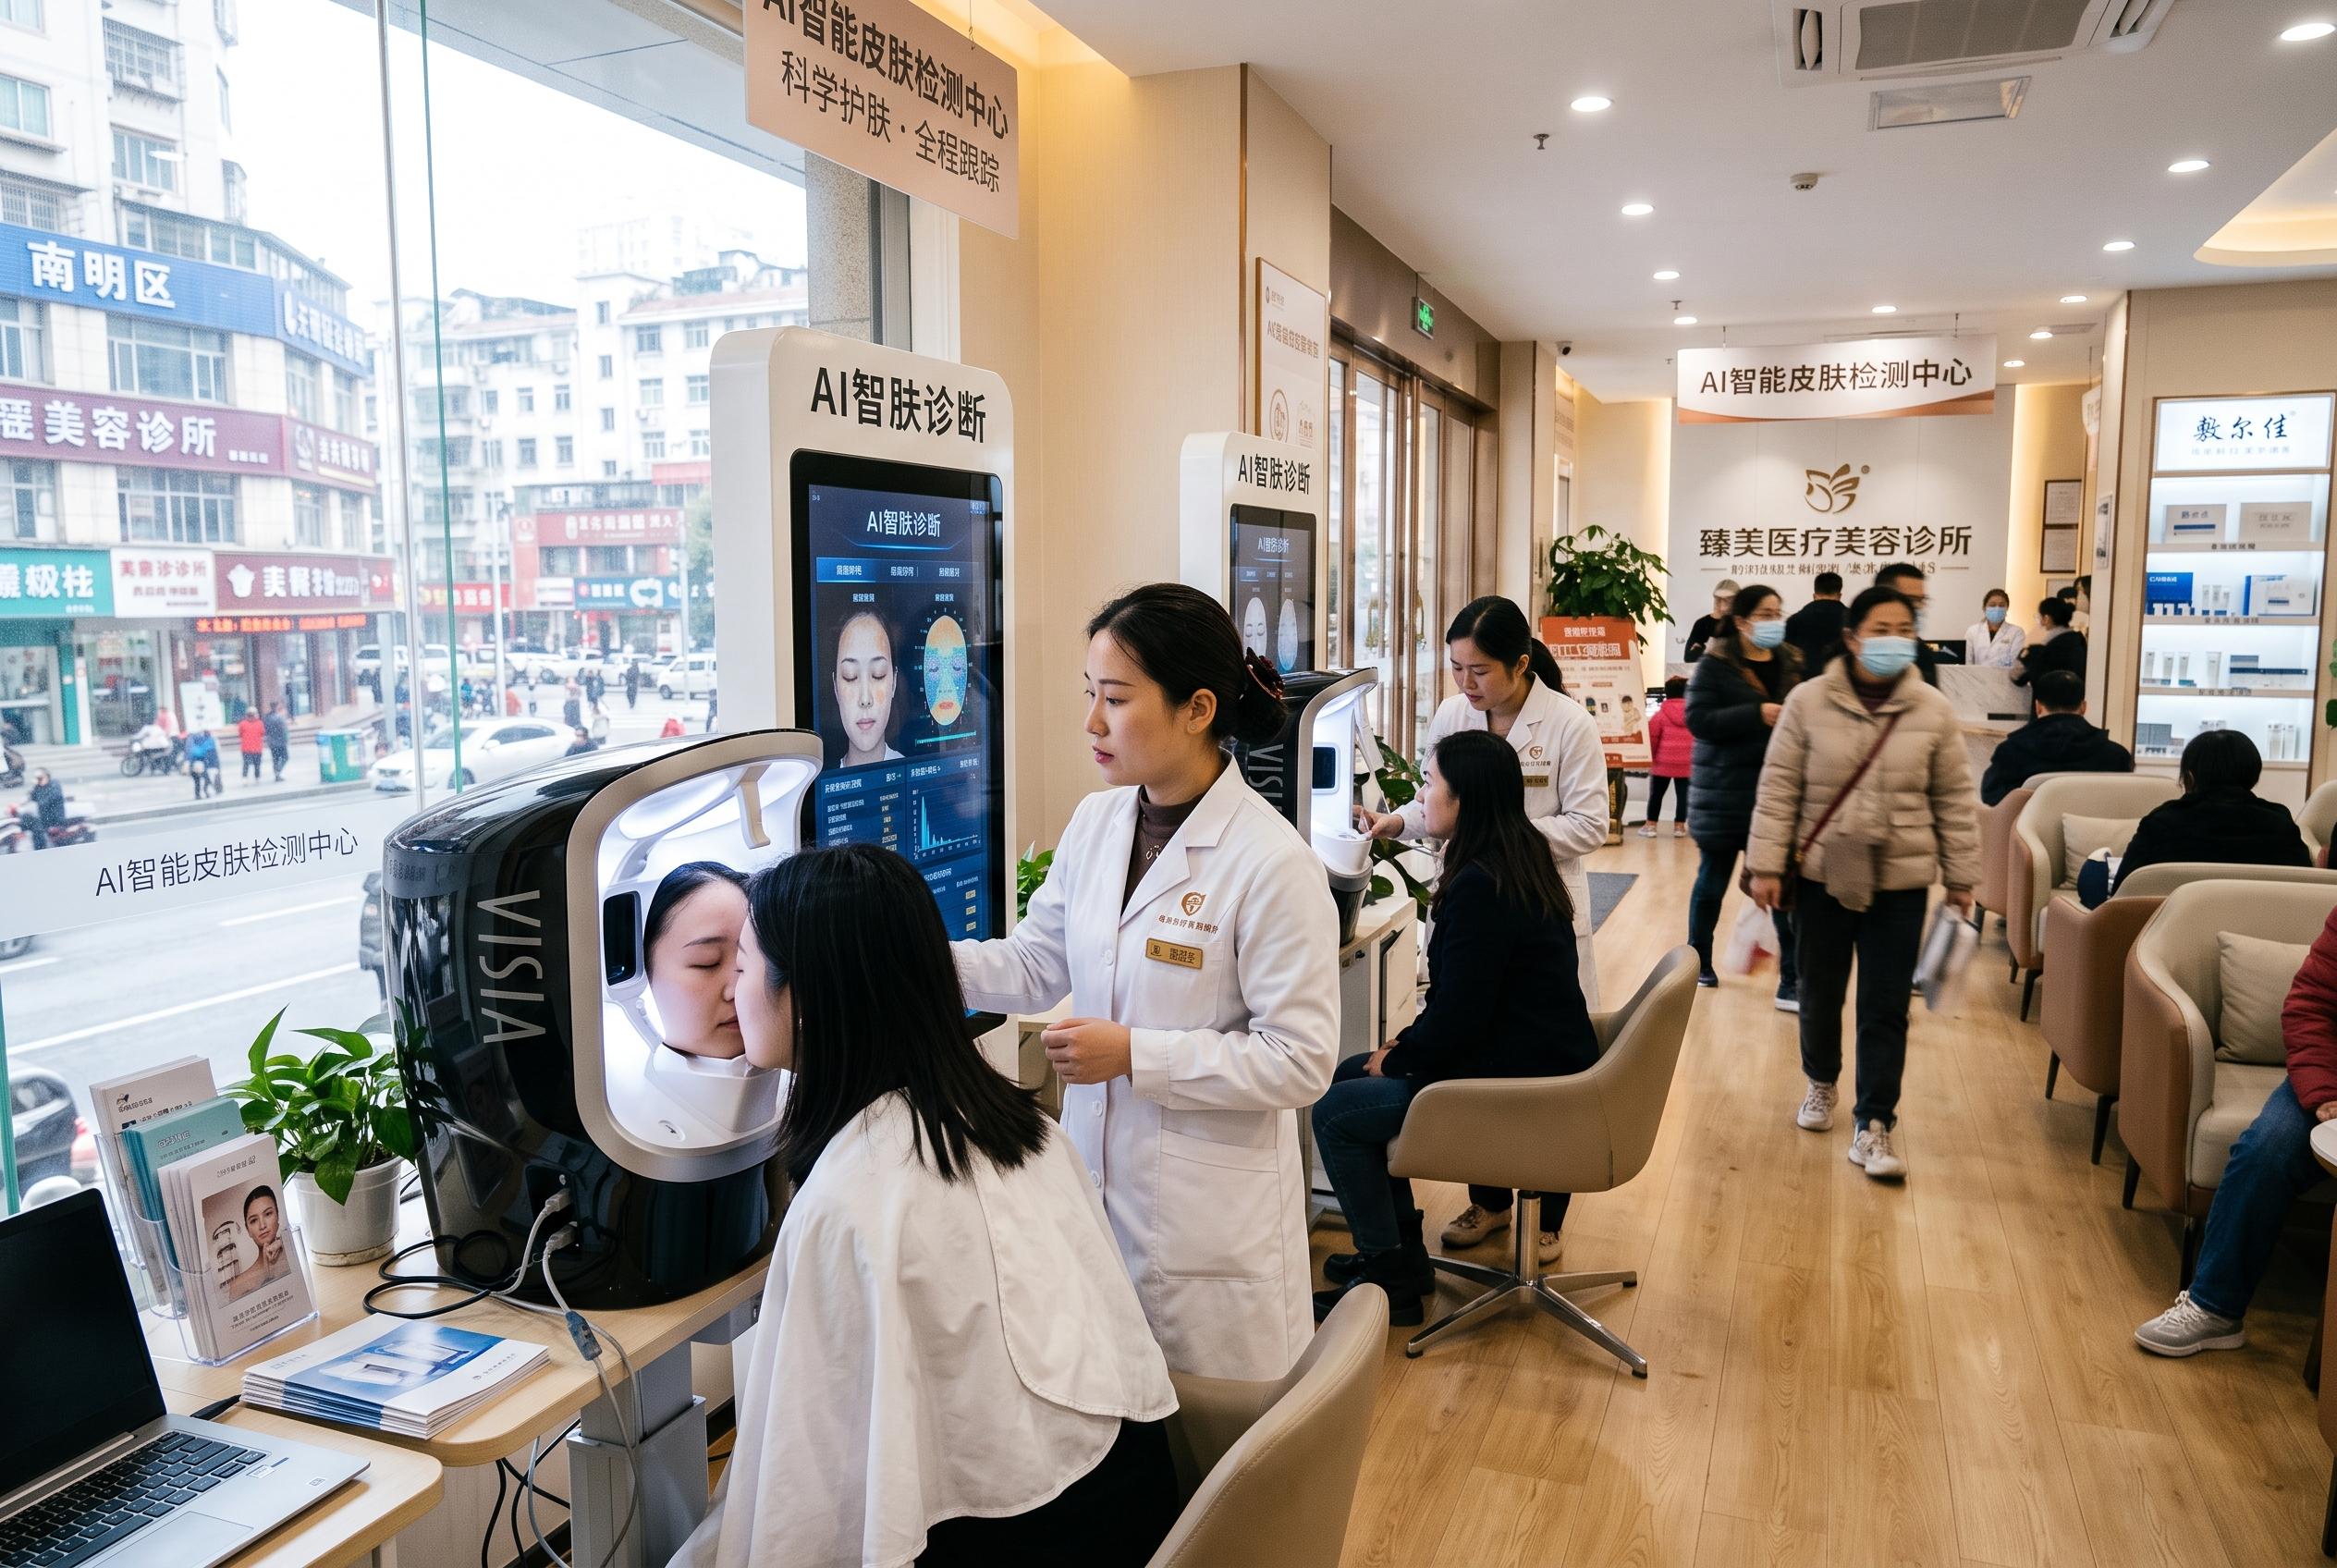
They say AI is increasingly embedded in RF systems to enhance monitoring, safety, and personalization. This means the conversation isn’t just about energy delivery anymore. Manufacturers are being pushed to develop systems that can support more controlled, patient-specific procedures.
It’s important to note that AI doesn’t replace human clinical judgment. Instead, it’s part of a broader effort to boost device performance and streamline treatment workflows. For buyers, the potential value of AI-enabled systems lies in how well these features support monitoring, safety, and usability.
This shift toward smarter medical electronics raises new sourcing considerations too. Companies may need to evaluate the quality of software integration, the robustness of device controls, manufacturing consistency, and a supplier’s capability to support maintenance and upgrades over time. These are considerations raised by this article’s analysis, not specific findings attributed to the report.
Geographical Expansion Beyond China’s Major Cities
Another key trend Frost & Sullivan highlights is geographic expansion within China. Demand isn’t just concentrated in the top-tier cities anymore; it’s spreading into second- and third-tier markets as well.
This diversification could expand the addressable market for RF devices. It might also influence how these products are designed, priced, distributed, and supported. These potential effects are part of this article’s analysis rather than stated findings from the report.
For distribution and logistics operators, this wider spread could mean new operational challenges. Equipment may need to reach more dispersed markets, while installations, training, ongoing maintenance, and after-sales service could become more important. The report doesn’t specify exactly which lower-tier cities are seeing growth, but the overall message is clear: demand is spreading beyond traditional urban centers.
This also underscores the potential importance of product usability. Equipment that’s easier to operate and maintain may be better suited to less developed markets, while regulatory compliance remains a universal must-have.
Chinese Companies Going Global
Finally, the third big shift is the push toward internationalization. Frost & Sullivan indicates that Chinese firms aren’t just content with exporting devices, they’re aiming to set up local production and build brands overseas.
This more ambitious, long-term approach to global expansion demands deeper commitment. Moving from exporting from China to establishing local factories, developing brands, navigating local regulations, setting up distribution channels, and supporting clients all require a much higher level of involvement.
For international buyers, this could open more opportunities to source Chinese-made aesthetic devices. However, evaluating suppliers may get trickier. They may want to examine how well a company is prepared regulatory-wise, its plans for overseas operations, its after-sales support, and how flexible it is in adapting products locally.
This trend toward overseas production and branding aligns with a wider shift in Chinese manufacturing, companies are increasingly competing on technology, market access, and building long-term relationships instead of just competing on low prices.
Frost & Sullivan’s findings fit into a broader pattern in the medtech sector. Simply having a good product may not be enough, vendors may need to combine advanced technology with solid regulatory readiness and local market access.
What It Means for the Industry and Sourcing
The overall message for manufacturers, distributors, and sourcing teams? The market is still expanding but becoming much tougher. Companies may need to invest across several areas, like product intelligence, regulatory compliance, quality control, market development, and international operations. Focusing on just one might not cut it anymore.
Distributors should revisit how they pick and evaluate products, prioritizing regulatory status, supplier stability, tech support, and fit for their target markets, alongside traditional factors like price and availability. For procurement teams, a structured evaluation process can help distinguish products that are just available from those that are sustainable long-term.
Frost & Sullivan’s other materials referenced here include recognition of RF systems used in minimally invasive procedures and adjacent aesthetic technologies such as ultrasound skin tightening. Those examples provide broader industry context but do not establish that this report builds on a history of tracking energy-based medical devices. [†2][†3][†4]
All of these developments signal that RF medical aesthetics are becoming more sophisticated. The integration of new technology, stricter regulation, domestic expansion, and overseas growth are all interconnected. Companies that can keep pace with these demands may be better positioned as the industry matures. Conversely, firms that can’t handle regulatory or technological pressures might find it increasingly difficult to compete.
Key Takeaways
- - China’s RF aesthetic market is moving toward a more regulated, competitive landscape.
- - Starting April 2026, Class III device registration costs could surpass 10 million yuan, putting pressure on smaller firms.
- - AI-driven features for monitoring, safety, and personalization are emerging as key development themes.
- - Demand is expanding beyond China’s core big cities into smaller, lower-tier markets.
- - Chinese companies are moving toward international markets with local production and branding.
- - Sourcing choices may go beyond price, emphasizing regulatory compliance, advanced features, and after-sales support.
Disclaimer: This article may have been created with AI assistance and reviewed by our editorial team. It is provided for general informational purposes only. Readers should verify information independently before relying on this content.
Sources: