- Memory shortages are worsening due to AI-focused manufacturing priorities
- Older DDR4 modules sometimes cost more than newer DDR5, defying expectations
- PC and industrial manufacturers are stockpiling parts amid soaring prices and limited supply
The Memory Supply Crunch Is Widening as AI Infrastructure Claims More Production
The squeeze on memory supplies is really intensifying, especially as artificial intelligence infrastructure takes up a bigger slice of the advanced semiconductor production pie. And honestly, this effect is not just limited to super high-end computing anymore, average PC components are also starting to see prices creeping up.
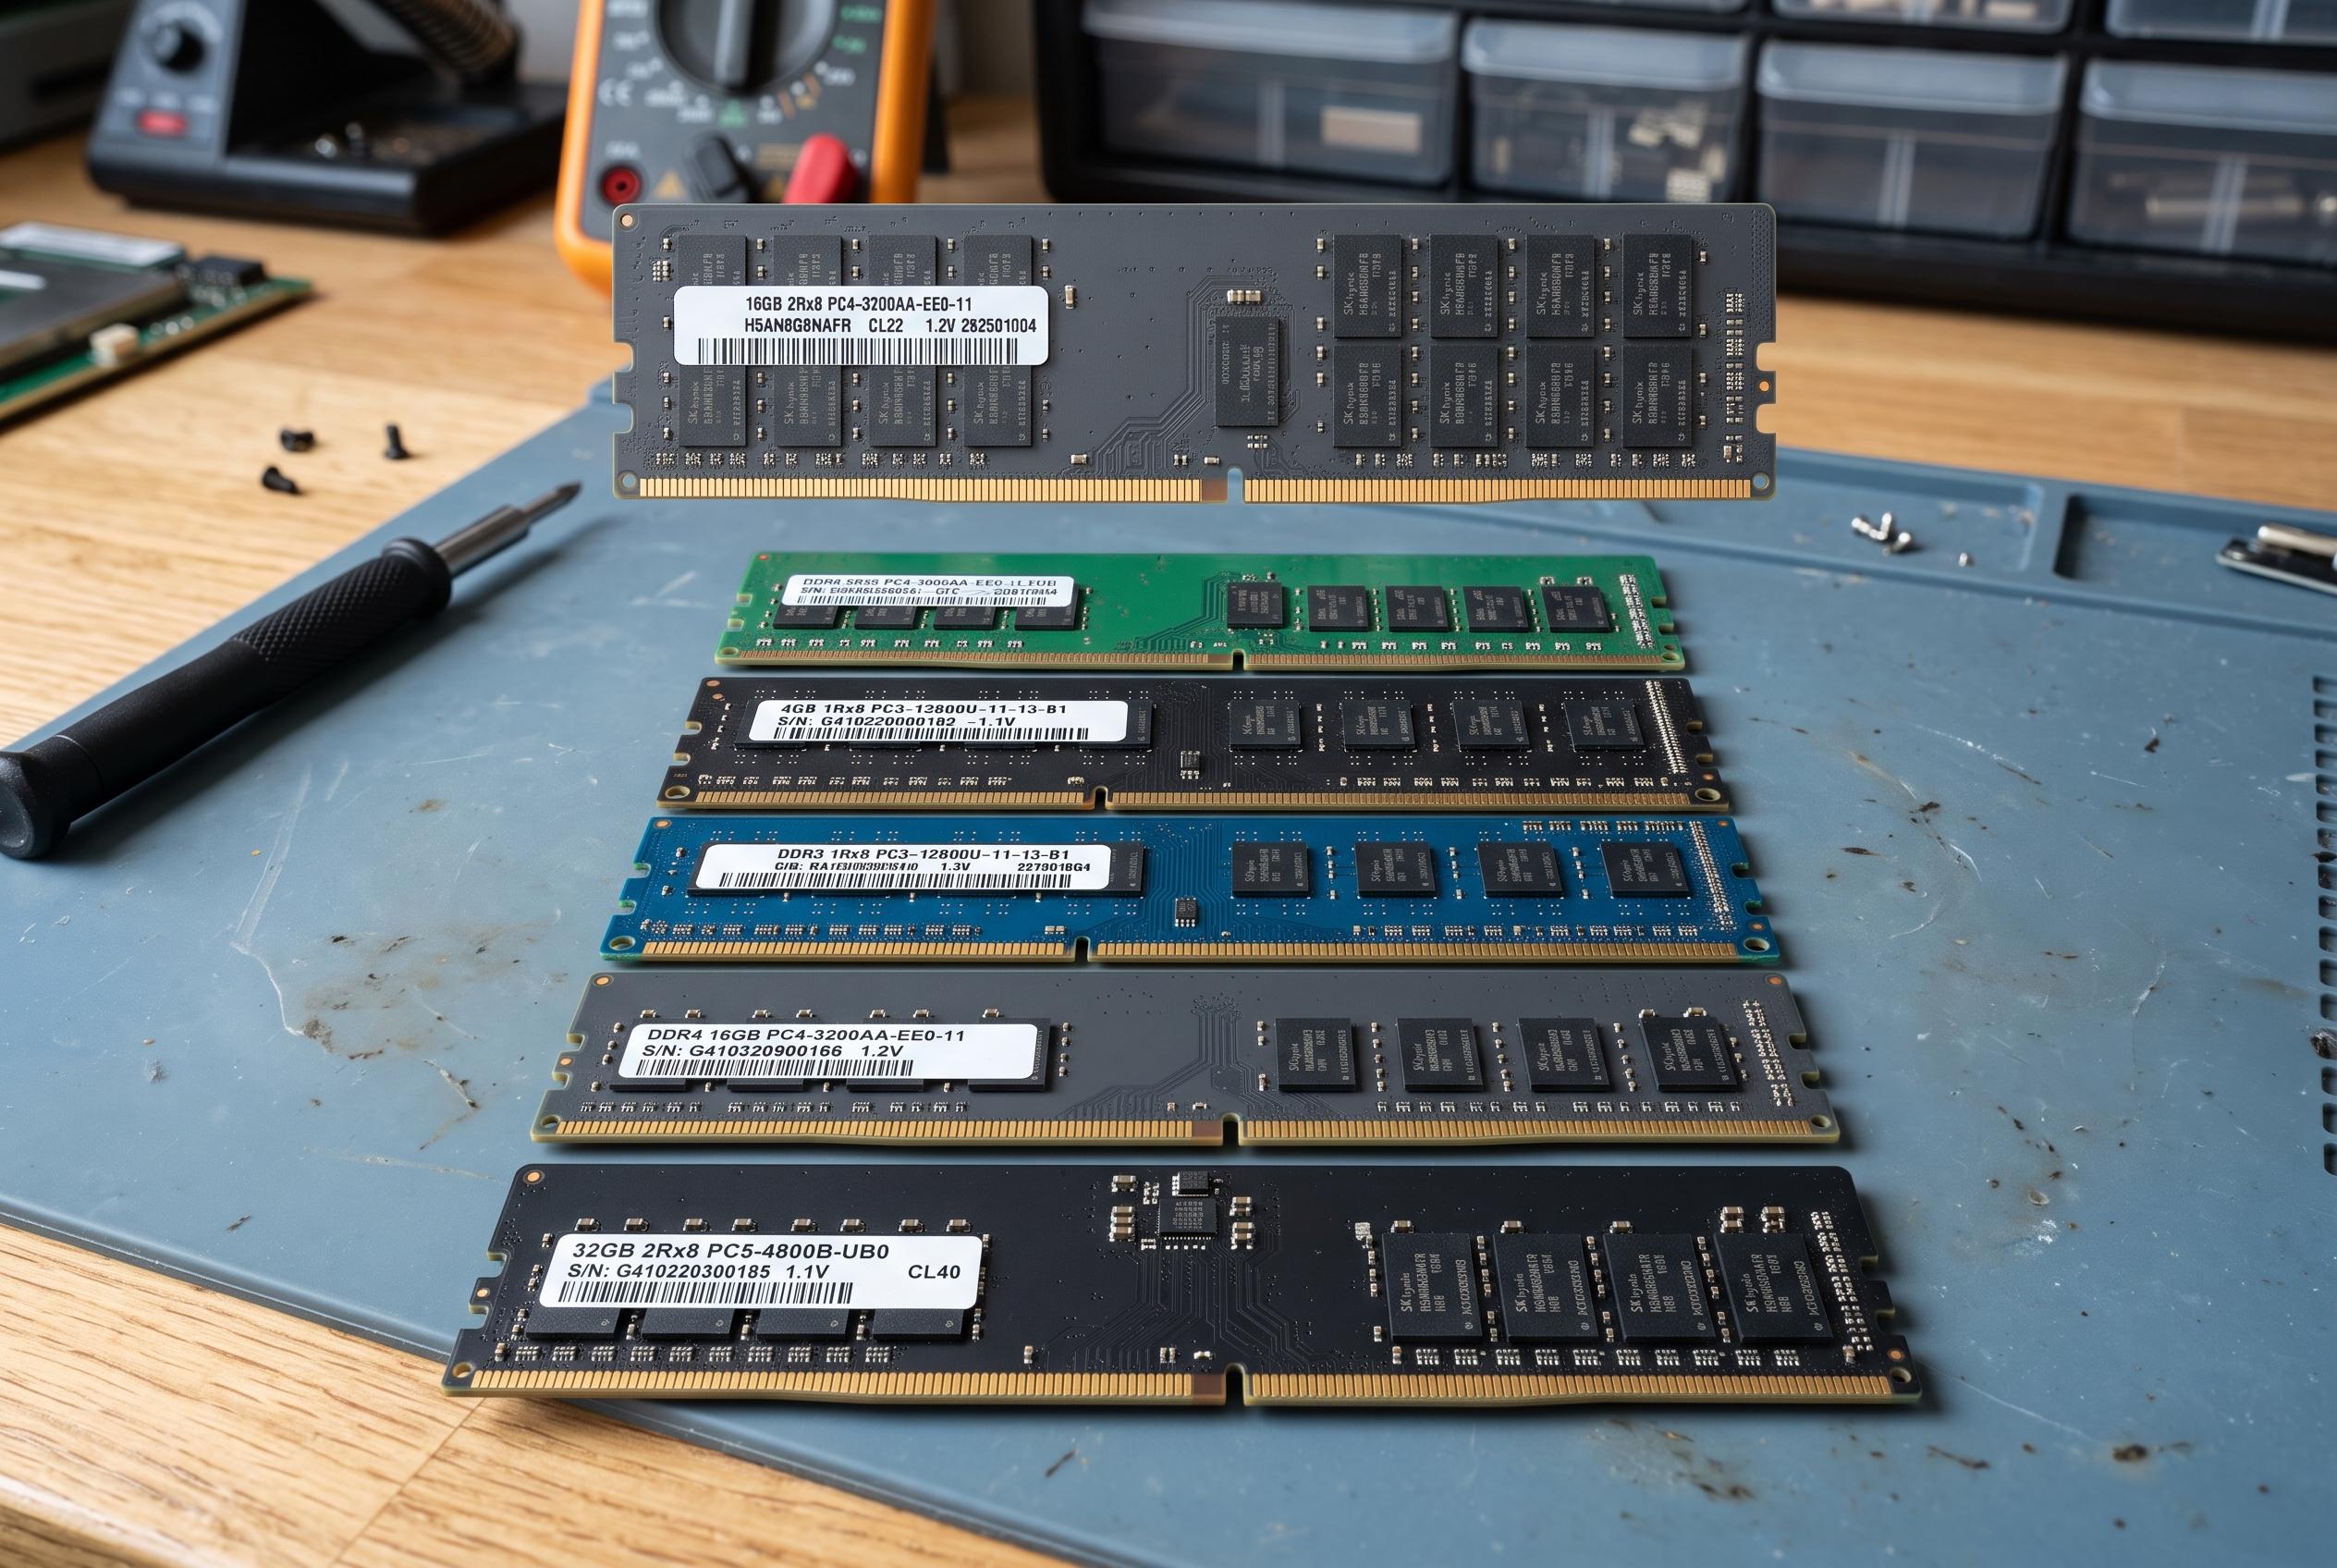
TrendForce reported that the contract price for a standard 8-gigabit DDR4 DRAM chip jumped by about 4.17 percent in August. To put that into perspective, that price is now about 8.6 times higher than what it was back in June 2016, and that’s quite a leap over the years. What’s really interesting here, though, is this unusual turnaround happening in the memory market: in some channels, older DDR4 modules are now selling for more than the newer DDR5 ones.
This situation matters a lot for companies involved in sourcing electronics, making PCs, industrial equipment and mobile hardware. Though memory is just one part of a finished gadget, sharp swings in component costs can throw off procurement plans, inventory levels, production expenses and even logistics schedules.
AI Infrastructure Is Changing How Memory Gets Supplied
Experts say that today’s supply shortages aren’t mainly driven by high PC demand but are more due to manufacturers shifting capacity toward AI-related products.
Specifically, companies are prioritizing high-bandwidth memory and server DRAM. These products are generally more profitable and heavily tied to AI accelerators. As more advanced manufacturing capacity goes into these specialized areas, less is left over for the traditional memory that is used in everyday PCs and other electronics.
This creates problems with supply, even if overall demand for PCs isn’t particularly high right now. It is not like consumers are suddenly buying loads more computers, it is more about production resources being diverted elsewhere. And that, in turn, tightens the available supply of certain memory types.
It is a crucial distinction, because in a typical demand-driven market, weaker demand might ease price pressures. But in this case, supply is limited because of where and what the manufacturers are choosing to produce. They are allocating their resources to more profitable areas, and that impacts the availability of older memory products.
And here’s the kicker: sometimes, older tech, say DDR4, can become more expensive than the newer DDR5. It is not just because of how old it is technically, either. Supply restrictions, manufacturing focus, inventory levels and buying behaviors all influence the final prices.
PC Manufacturers Are Stockpiling
According to Tom’s Hardware, the shift in manufacturing focus has shrunk the amount of DDR4 available enough that PC makers are trying to build bigger inventories, aiming for more than 10 weeks’ worth of stock.
This makes sense given their worries about future shortages. When manufacturers think a certain component might become hard to get later, they tend to buy more upfront. That, of course, can ratchet up competition among buyers and further tighten the supply.
For PC companies, building up inventory is not just a matter of paying more; it involves planning for storage, scheduling purchases, managing cash flow and coordinating logistics. Having more than 10 weeks’ worth of inventory offers some buffer against shortages but also means tying up resources early, before the products even hit the market.
Especially for electronics companies that work on tight schedules, even a small shortage of a key component can delay assembly lines or complicate distribution if replacements are not readily available. So, securing memory supplies, in spite of rising prices, remains a high priority.
TrendForce has already upped its forecast for third-quarter PC DRAM prices. They now expect prices to jump by 18 to 23 percent, compared to an earlier estimate of just 15 to 20 percent. Some deals in August reportedly saw increases of 23 to 28 percent. That shift in outlook highlights just how rapidly market expectations are changing. Buyers who planned for smaller increases might now need to brace for even higher costs. Meanwhile, suppliers are operating in a tight market that is supporting those higher prices.
The Market’s Not Moving Uniformly
The unevenness is also evident across different NAND flash product lines. Prices aren’t increasing equally , some products are seeing sharper jumps than others.
TrendForce reported that 128-gigabit MLC NAND chips rose just about 1.42 percent in August, which suggests that buyers are less willing to accept big price hikes in that segment. That resistance creates an interesting contrast: while some components are climbing sharply, others are more resistant.
Older SLC parts, for instance, continue to see substantial gains. Data shows that 4-gigabit chips led the pack, with 2-gigabit and 8-gigabit versions both rising over 20 percent. Basically, the pattern here reflects a familiar scenario in semiconductors: newer 3D NAND lines get most of the investment and attention, while support for legacy parts diminishes. That does not mean there is no demand for older memory, just that fewer manufacturers are willing or able to support it, perhaps because they see it as less profitable or strategically important.
This can create headaches for companies that build products around these older technologies. Even if a component has been reliable, stable and well-understood, if fewer suppliers are supporting it, sources may become scarcer, costs higher and procurement longer.
Legacy Components Still Critical for Many Systems
The shortage really hits home because many industrial and embedded systems depend heavily on older memory types. In many cases, you just can’t swap out these components for newer models without some serious re-engineering.
Switching memory types is not just swapping chips; it can mean redesigning hardware, reevaluating firmware and undergoing an expensive qualification process before production can resume. For industrial equipment, that process can be lengthy and costly.
TrendForce notes that demand still remains for sectors like telecom gear and smart meters. These markets tend to change less rapidly and often require expensive qualification procedures, so manufacturers are still buying older memory, including DDR4 and SLC, despite newer options being more prominent elsewhere on the market.
This ongoing relevance of older memory explains why they continue to be a commercial necessity. Their importance is not solely about being the latest technology but also about supporting existing systems, where the costs and complexity of change can be prohibitive.
For sourcing teams, this creates a tricky balancing act: do you pay more now for familiar, proven components, or do you risk redesign, extended qualification or production delays? Sometimes, paying a premium to stick with older components makes more sense than risking delays or failures caused by trying to switch to newer parts.
And it is not just in industrial or embedded systems. These principles apply across many other categories, telecom, industrial controls, smart meters, where reliance on legacy parts continues.
September Outlook: Prices Expected to Climb Again
Looking ahead into September, TrendForce predicts further sharp price increases for DRAM. They expect SLC NAND to see only mild gains, while MLC prices might stay fairly steady.
This forecast underscores the growing gap across different memory segments. DRAM is under ongoing strong upward pressure, especially where production capacity has shifted to support AI workloads. Meanwhile, SLC NAND is expected to see only minor increases after earlier jumps, and MLC pricing should stay around current levels.
It also highlights the importance of understanding specific product categories. General statements about the memory market often hide these big differences, between DRAM and NAND, between new and old products, or between high-volume PC components and niche industrial parts.
For buyers, the challenge is figuring out which categories are most affected by supply constraints. PC manufacturers are already buying more than 10 weeks of DDR4, but companies relying on older embedded or industrial memory might face very different challenges, especially if those parts are not easily substituted.
This market reversal also serves as a good reminder: just because a product is newer does not always mean it is more expensive. The fact that DDR4 is selling at a higher price than DDR5 in some channels shows that supply conditions often outweigh the tech generation itself. When manufacturers shift capacity, even older parts can become the more constrained and costly items.
What This Memory Squeeze Means for Buyers in Electronics
So, what are the practical implications for sourcing and logistics? First off, age and technology level don’t always tell the whole story. Sometimes, older memory can become more expensive when production slows and demand remains steady.
Second, the priorities in AI infrastructure are spilling over into the broader market, reducing the availability of some standard products used in computers and embedded systems.
Third, planning inventories well ahead is becoming increasingly critical. PC makers are already stocking more than 10 weeks of DDR4 due to concerns over future supply. For other sectors, especially industrial or embedded systems, there are different hurdles, parts that can’t be easily swapped or require lengthy qualification processes.
Finally, substitution is not always simple or quick. Many industrial and embedded systems depend on tried-and-true components. Replacing them often entails redesign work and additional certification steps, which cost time and money.
In essence, the memory market remains patchy and unequal. Prices for DRAM are expected to rise sharply once again in September, while SLC NAND might see only marginal increases, and MLC stays fairly steady. For electronics manufacturers, the real key is not just watching prices go up. It is understanding which components are under the most pressure, how quickly those conditions change and how feasible it is to replace certain parts.
Frequently Asked Questions
Why are DDR4 prices climbing so quickly? Manufacturers are shifting their capacity toward higher-bandwidth memory and server DRAM, which are more profitable and increasingly linked to AI accelerators. That has cut into DDR4 availability.
Is strong PC demand fueling the shortage? Not exactly, say analysts; it is more about how manufacturers are deciding to allocate their production resources.
How can older DDR4 sometimes cost more than DDR5? Pricing’s driven by supply and demand, not just tech age. Reduced DDR4 output has made it more constrained in some channels, pushing prices higher.
Which NAND products are most affected by price increases? Older SLC NAND chips have gone up significantly. TrendForce mentions that 4-gigabit chips lead the gains, with 2- and 8-gigabit versions climbing over 20 percent.
Which sectors are still heavily reliant on older memory? Telecom equipment and smart meters are key examples, along with many industrial applications that need stable, mature memory solutions.
What’s the outlook for September? TrendForce predicts DRAM prices will increase sharply again, SLC NAND might see small gains and MLC prices are likely to stay steady.
Disclaimer: This article may have been created with AI assistance and reviewed by our editorial team. It is provided for general informational purposes only. Readers should verify information independently before relying on this content.
Sources: