Vietnam’s manufacturers and suppliers are gaining a new route to working capital as MB expands multi-tier supply chain finance across domestic business networks. The digital model is designed to connect larger companies with tier-one, tier-two, and deeper suppliers, helping capable smaller firms overcome collateral, paperwork, and credit-history hurdles.
Vietnam's supply chains are growing, but capital isn't reaching everyone
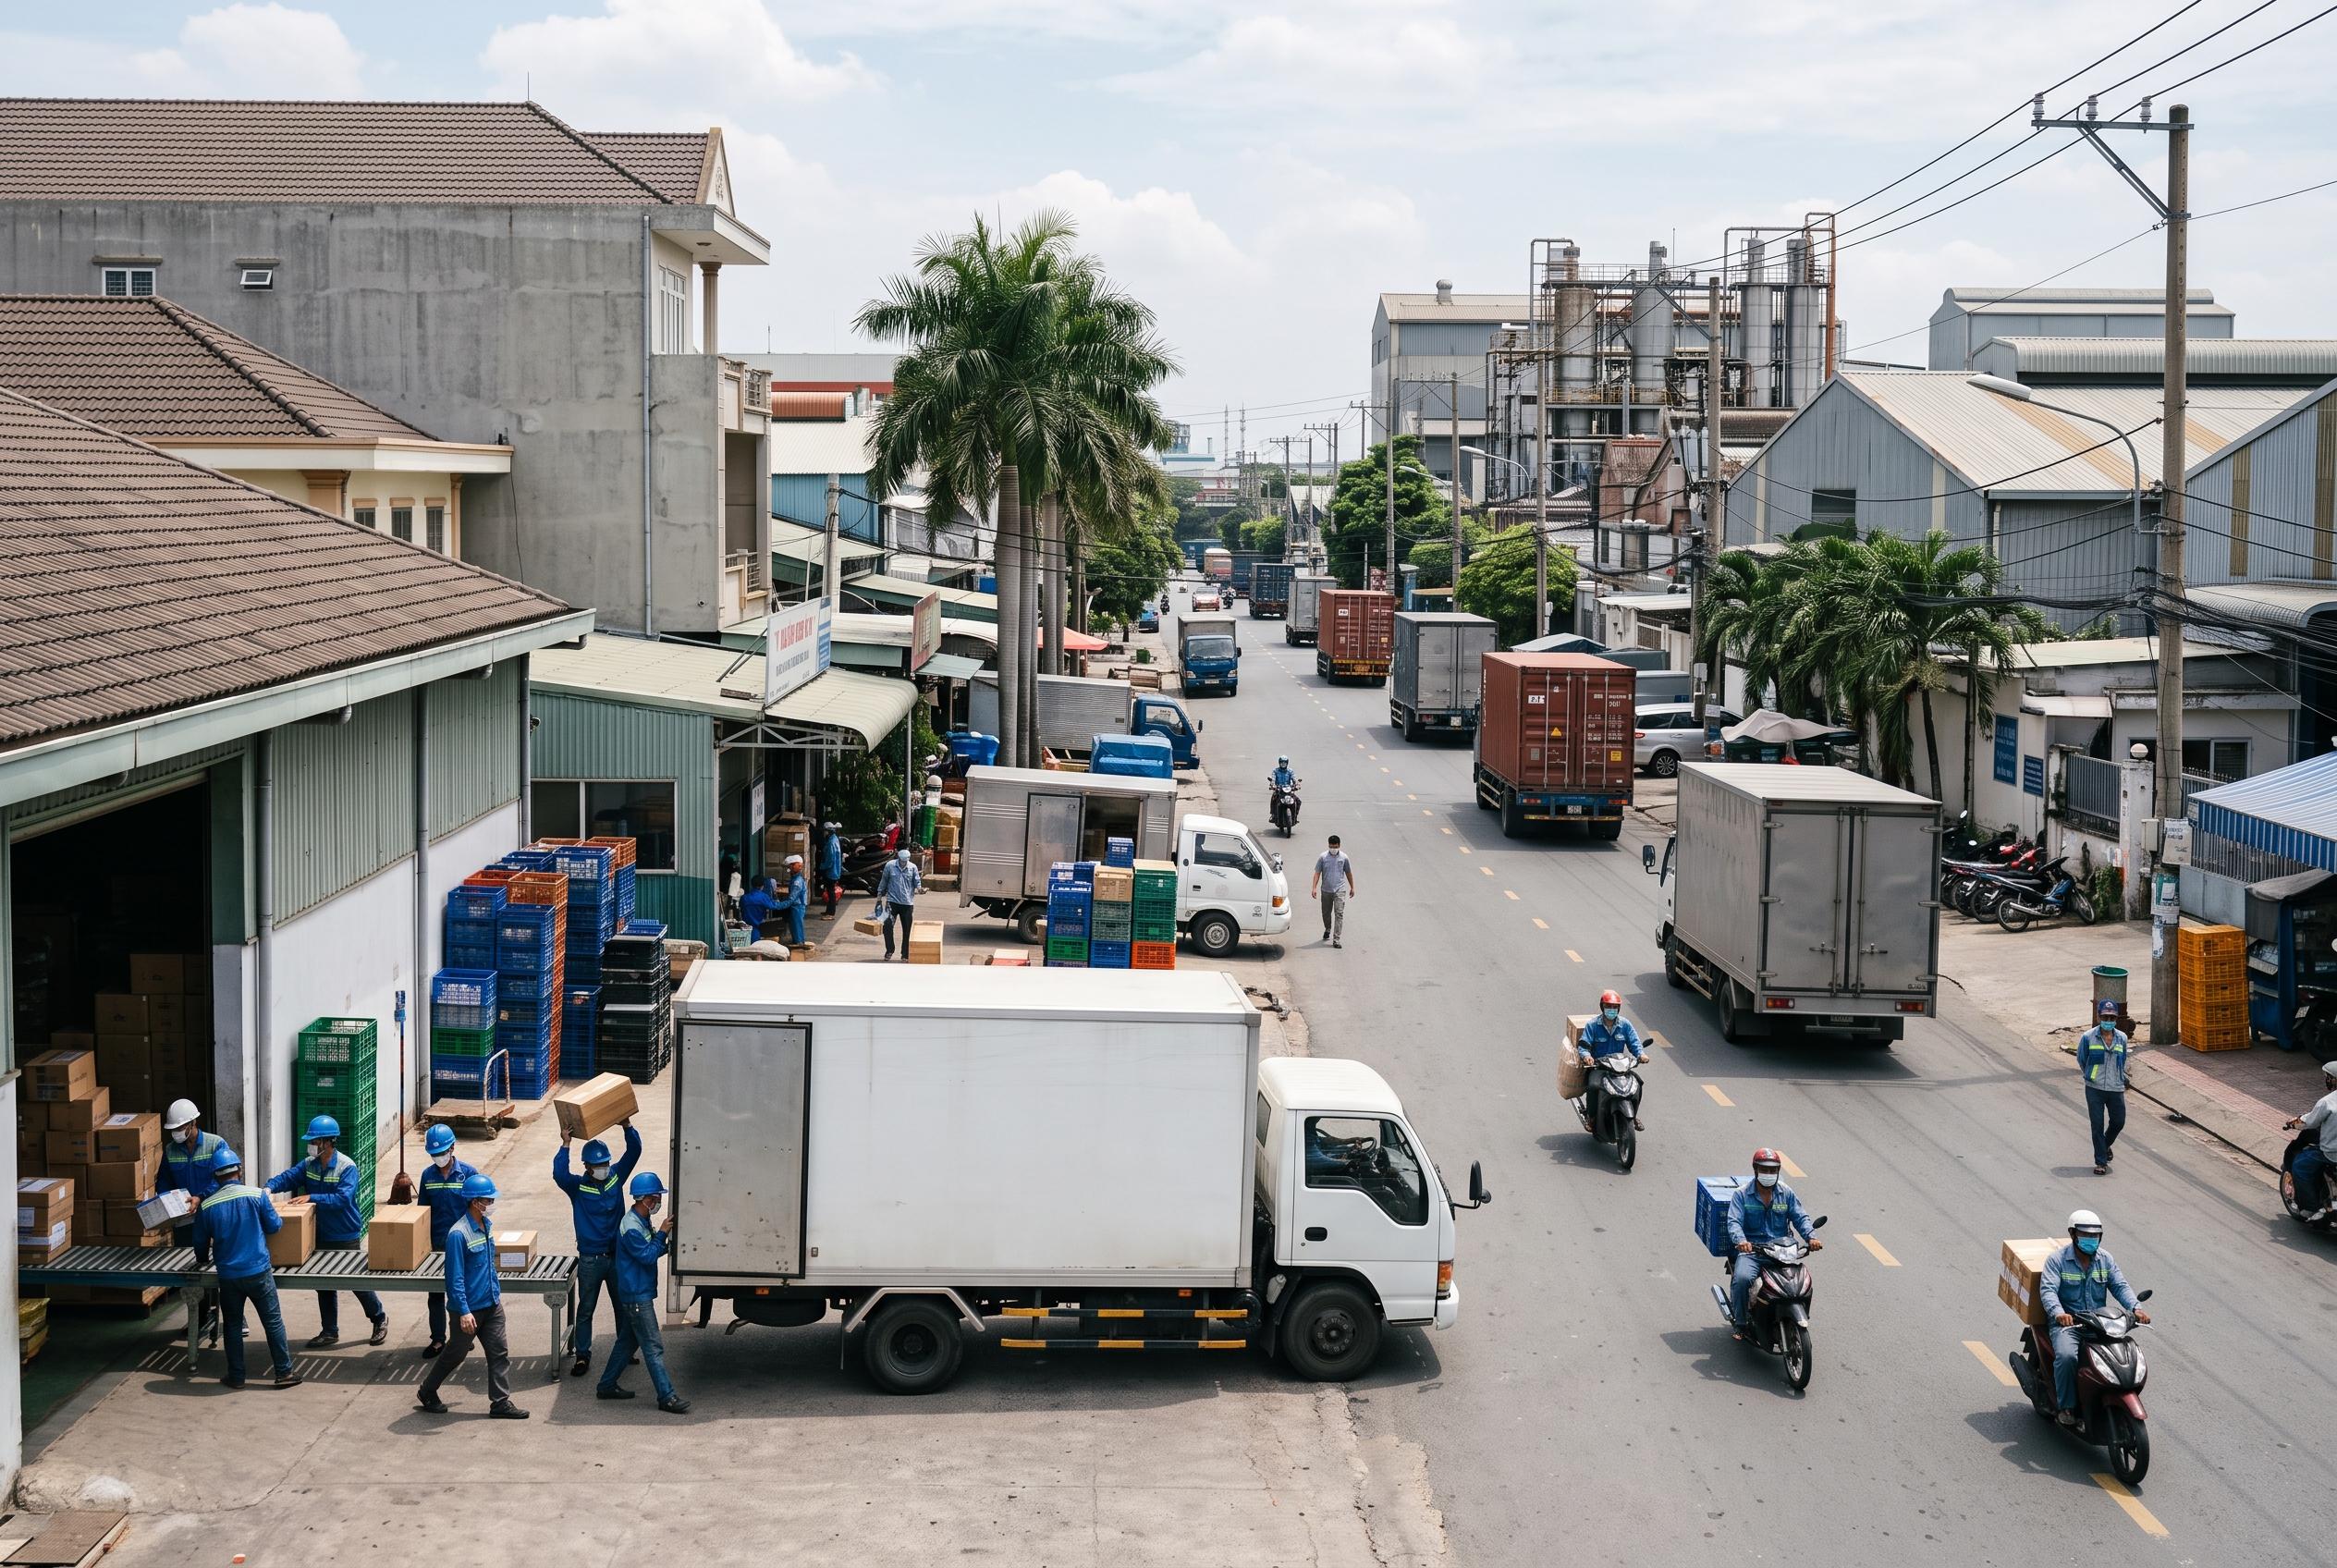
Vietnam's role in global manufacturing is expanding, with investment flowing into electronics, supporting industries, consumer goods, energy, and export production. That growth creates room for local companies to become more important suppliers, but it also raises the bar for delivery speed, quality, financial discipline, and production capacity.
The awkward part is that many smaller businesses already have orders and functioning operations, yet still struggle to borrow. Traditional lending can place heavy weight on collateral, audited accounts, and established credit records, leaving otherwise viable suppliers waiting on the sidelines. Industry coverage from The Investor and Vietnam.vn highlights this gap as one of the central reasons deeper supply-chain finance is gaining attention.
That matters because a disruption at a smaller supplier can travel quickly through the network. A factory may have a full order book, but without cash to buy materials, pay workers, or expand output, the opportunity can still slip away.
MB is taking supply-chain finance beyond the top tier
MB's new approach is built around a multi-tier digital platform rather than a simple bank-to-company relationship. The system is intended to connect a central enterprise with tier-one suppliers, then extend through tier two, tier three, and potentially further levels of the chain.
The bank's model begins with a suitable core company and its surrounding commercial ecosystem. As suppliers and distributors join, purchase and sales transactions can be confirmed on the platform. That gives MB a clearer view of what is actually being bought, sold, delivered, and paid for, according to reporting from Vietnam.vn and The Investor.
For smaller firms, the appeal is straightforward. Financing can be linked to real trading activity instead of depending entirely on property or a long borrowing history. In practical terms, that could mean more breathing room between receiving an order and getting paid.
Why transaction data could change the lending conversation
Supply-chain finance isn't a brand-new idea, but deeper digital connectivity gives banks more information to work with. Rather than assessing each company as an isolated borrower, the platform can look at relationships, invoices, payment flows, and activity across the wider network.
That approach could make working capital more responsive. A supplier with regular orders from a financially strong buyer may present a different risk profile from a small company with no verified commercial connection. MB General Director Pham Nhu Anh said the model requires technology to support customer identification, transaction authentication, cash-flow control, risk management, and data security, according to coverage of the launch.
The technology stack is expected to include automation, big-data tools, and blockchain-based verification. Those labels can sound grand, but the useful test is much simpler: can the system confirm a genuine transaction quickly, protect sensitive information, and reduce repetitive manual checks? If it can, the benefit should be felt in faster decisions and cleaner cash-flow management.
The "three no's" model has obvious SME appeal
MB says eligible businesses can access a flexible financing structure built around three features: no separate credit-limit approval, no collateral requirement, and no debt obligation. The idea is to provide access tied to confirmed supply-chain activity rather than making every small business shoulder a conventional loan structure.
That could help suppliers finance raw materials, maintain production, and meet delivery schedules without tying up valuable assets. It may also allow companies to manage receivables and payments in one place, which is particularly useful when cash arrives weeks after goods leave the factory.
Still, businesses should read the terms carefully. No collateral doesn't mean no conditions, and transaction-linked finance will depend on accurate records, verified relationships, and the strength of the wider chain. A supplier considering the service should check fees, repayment triggers, payment timing, data permissions, and what happens if an order is delayed or disputed.
Security and trust will decide whether the model scales
Connecting multiple companies creates a much bigger data environment, so access control becomes essential. A supplier shouldn't see information that belongs to another participant, while the bank still needs enough visibility to verify transactions and manage risk.
MB says its platform is designed with tightly controlled permissions and an automated end-to-end process. Reporting also points to technology such as blockchain and big data as tools for strengthening verification and transparency. The promise is a quieter, cleaner back office, with fewer spreadsheets moving around and less manual intervention.
For the model to become a meaningful part of Vietnam's business infrastructure, adoption will matter as much as software. Large companies need to invite suppliers into the system, smaller firms need confidence that participation is worthwhile, and everyone needs clear rules around privacy and dispute resolution. That's the unglamorous groundwork that can turn a clever platform into a useful commercial habit.
A promising bridge between global orders and local businesses
Vietnam's supply-chain opportunity won't be measured only by how many multinational companies arrive. It will also depend on whether domestic suppliers can grow alongside them. Better access to working capital could help smaller manufacturers invest, deliver more reliably, and move into higher-value roles.
MB's multi-tier strategy is therefore more than a new banking feature. It reflects a broader shift toward financing based on connected business activity, where the strength of a commercial network can help unlock funds deeper down the chain. The approach still needs careful execution, but it points in a useful direction for companies that have demand yet lack traditional borrowing power.
For business owners, the practical lesson is to keep transaction records accurate, maintain clear buyer relationships, and understand exactly how platform data will be used. In a fast-moving supply chain, good paperwork may not be glamorous, but it can be the key that opens the door.
Disclaimer: This article may have been created with AI assistance and reviewed by our editorial team. It is provided for general informational purposes only. Readers should verify information independently before relying on this content.